By the Drivers Compass editors · Updated October 31, 2026
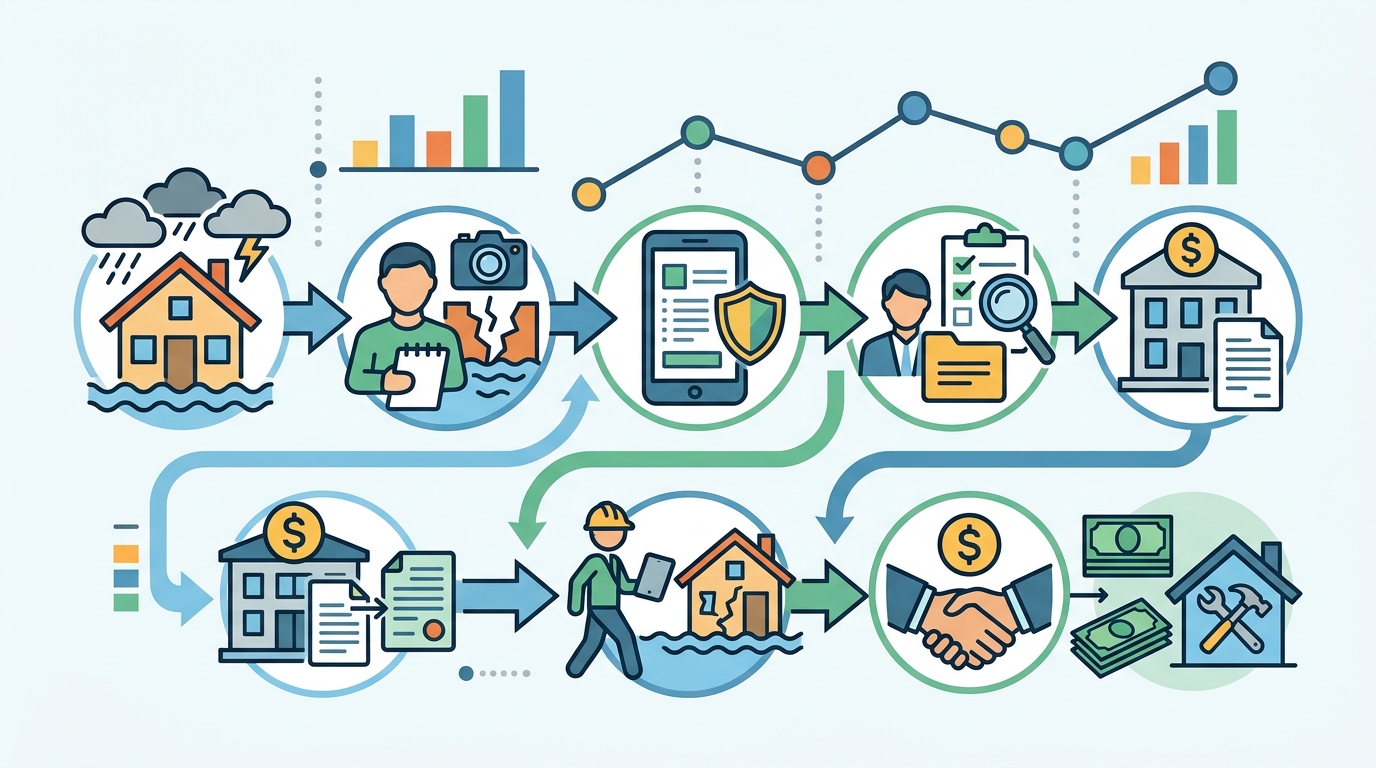
Flood and named-storm claims run on deadlines you can miss in the first two months. On a National Flood Insurance Program policy, prompt written notice to FEMA comes first, and FEMA requires a signed Proof of Loss within 60 days of the loss (FEMA, 2025-01-21; Whitley Law Firm, undated).
What the insurer owes you back — acknowledgment, inspection, a copy of the estimate, a pay-or-deny decision — is set by state law and varies sharply. Florida writes those duties into statute with specific day counts; many states do not.
What Happens After You File
Your report creates a first notice of loss, a claim number, and a case reserve — the insurer's internal estimate of what the file will cost, carried on its books and revised as the investigation develops. The reserve is an accounting entry, not an offer, and it is not disclosed to you.
The file then goes to an adjuster, often a catastrophe adjuster on deployment after a named storm rather than local staff. In Florida, the licensed adjuster assigned to conduct a physical inspection must give you a printed or electronic document showing their name and state adjuster license number (The Florida Senate, 2023). Keep it; it is how you identify who inspected what.
Two investigations run at once. The coverage investigation asks whether the policy responds at all — which turns on the flood or water-damage exclusion in a homeowners policy, the hurricane or named-storm deductible endorsement, and, for a vehicle, whether comprehensive (other-than-collision) coverage was in force. The damage investigation prices the loss.
If the policy is an NFIP Standard Flood Insurance Policy, a Write Your Own insurer may handle the file but FEMA's rules govern: a signed and completed proof of loss is generally required, and a signed, sworn proof of loss is a condition of payment (unitedlawpa.com, undated; deniedfloodclaim.com, undated).
All of that is first-party adjusting — your insurer, your policy conditions. A third-party claim against someone you allege caused the flooding is liability adjusting, where state prompt-payment duties to a policyholder may not reach you and the adjuster owes duties to their own insured.
Step-by-Step Filing Process
- Policyholder — give prompt written notice, same day if you can. On a flood policy the first required action is prompt written notice to FEMA (Whitley Law Firm, undated). On an auto or homeowners claim, file through the insurer's claims department or claims app and record the claim number and the time you reported. Your policy's duties after loss condition is what makes notice mandatory.
- Policyholder — photograph and video everything before cleanup. Record the waterline on an interior wall, door panel, or seat back within the first 24 to 48 hours, before mold and corrosion change the evidence.
- Policyholder — mitigate further damage and keep the receipts. The duties after loss condition requires reasonable steps to prevent more loss; pump-out, board-up, and tow invoices are usually reimbursable. Discard nothing unphotographed.
- Insurer — acknowledge the claim. In Florida, within 7 calendar days of receiving a claim communication, unless payment is made in that period or factors beyond its control prevent it (The Florida Senate, 2023). Other states set different periods, or none.
- Insurer and adjuster — investigate and inspect. In Florida the insurer must begin a reasonably necessary investigation within 7 days of receiving proof-of-loss statements and, where physical inspection is involved, inspect within 30 days of receiving them (The Florida Senate, 2023).
- Policyholder — complete, sign, and submit the Proof of Loss. On an NFIP claim it is due within 60 days of the date of loss unless FEMA extends it (FEMA, 2025-01-21; deniedfloodclaim.com, undated). List every damaged item and amount; the form is sworn.
- Adjuster — produce a detailed estimate. In Florida you must receive a copy within 7 days after the adjuster generates it (The Florida Senate, 2023). Read the line items and the depreciation column before agreeing to anything.
- Body shop or contractor — document hidden damage, then file a supplemental claim. Damage to wiring, modules, and subfloors surfaces weeks later; items missed on the Proof of Loss can be submitted in a supplemental claim (FEMA, 2025-01-21).
- Insurer — pay or deny. In Florida, within 60 days of notice of an initial, reopened, or supplemental property claim, absent factors beyond its control; a later payment bears interest at the rate in section 55.03 (The Florida Senate, 2023).
- Policyholder — dispute in writing if the number is short. Where payment is below the insurer's own detailed estimate, a Florida insurer must explain the difference in writing (The Florida Senate, 2023). Use that letter, your own estimates, and the appraisal clause in your policy before escalating to your state insurance department's consumer complaint portal.
Documents and Evidence to Gather
- Declarations page showing your deductible and any hurricane or named-storm deductible endorsement.
- Claim number, plus the date and time you gave notice.
- The adjuster's name and state adjuster license number, which Florida requires the adjuster to hand you (The Florida Senate, 2023).
- The signed Proof of Loss form, with your submission date.
- Dated waterline photos — interior wall, or the seat and door panel of a flooded vehicle.
- A continuous video walkthrough recorded before any pump-out or cleanup.
- The police report number, if law enforcement responded.
- Towing and storage invoices from the tow yard.
- A photo of the odometer and the VIN plate.
- A line-item estimate from a licensed body shop or contractor, parts and labor broken out.
- Mitigation receipts: pumping, drying, tarping, board-up.
- A contents inventory listing each item's purchase date and price.
- Rental car or additional living expense receipts.
- Your lienholder or mortgage loan number, since a loss payee is named on the check.
- The insurer's detailed estimate and any written explanation of a lower payment.
Typical Claims Timeline
The day counts below are statutory duties in Florida under the 2023 version of section 627.70131, plus the federal Proof of Loss deadline. Your state may set a different period or leave timing to the policy.
| Milestone | Day range | Where the deadline comes from |
|---|---|---|
| Acknowledgment of your claim communication | Within 7 calendar days | Florida statute (The Florida Senate, 2023) |
| Investigation begins after proof-of-loss statements | Within 7 days | Florida statute (The Florida Senate, 2023) |
| Physical inspection of the property | Within 30 days of receiving proof-of-loss statements | Florida statute (The Florida Senate, 2023) |
| Copy of the detailed estimate sent to you | Within 7 days of the adjuster generating it | Florida statute (The Florida Senate, 2023) |
| Signed Proof of Loss due on an NFIP flood claim | Within 60 days of the date of loss, unless FEMA extends | FEMA (2025-01-21); deniedfloodclaim.com (undated) |
| Pay or deny the claim, in whole or part | Within 60 days of notice of an initial, reopened, or supplemental claim | Florida statute (The Florida Senate, 2023) |
| Interest accrues on a late payment | After day 60 | Rate set in section 55.03 (The Florida Senate, 2023) |
These periods move. The 2020 version of the same Florida statute gave insurers 90 days to pay or deny before the legislature shortened it to 60 (The Florida Senate, 2020). A Florida insurer may also run past the deadline where the failure to pay is caused by factors beyond its control, which after a major named storm can include access restrictions.
Common Mistakes That Delay Payout
- Pumping out, gutting, or scrapping the vehicle before the inspection. In Florida the insurer has up to 30 days from the proof-of-loss statements to inspect (The Florida Senate, 2023). Remove the evidence first and the adjuster prices from your photos, which narrows what you can later dispute.
- Treating a phone report as your Proof of Loss. On an NFIP claim the signed, sworn proof of loss is a condition of payment under the Standard Flood Insurance Policy (deniedfloodclaim.com, undated). Notice alone does not satisfy it, and the 60-day clock runs from the date of loss, not the adjuster's visit (FEMA, 2025-01-21).
- Guessing at values or padding the contents list. A Florida insurer may void the policy where the policyholder, with intent to injure, defraud, or deceive, provides false, incomplete, or misleading information using electronic claim investigation methods (The Florida Senate, 2023).
- Leaving hidden damage off the form and assuming it is lost. It can still go in a supplemental claim (FEMA, 2025-01-21), but that restarts the review and the pay-or-deny period for that supplemental claim.
- Cashing the check without reading the estimate. If payment is below the insurer's own detailed estimate, a Florida insurer must explain the difference in writing (The Florida Senate, 2023). Asking afterward gives up your best leverage: the insurer's own numbers.
- Arguing by phone only. Verbal disagreements leave no record of when you objected. A dated written demand to the claims adjuster, naming the disputed line items and amounts, is what an appraisal demand or a state insurance department complaint is later built on.
Questions
How long do I have to file a Proof of Loss on a flood claim?
For an NFIP flood claim, FEMA requires a signed Proof of Loss within 60 days of the loss (FEMA, 2025-01-21). Prompt written notice to FEMA comes first (Whitley Law Firm, undated). Under the Standard Flood Insurance Policy the deadline is 60 days after the flood unless FEMA extends it, and a signed, sworn proof of loss is a condition of payment (deniedfloodclaim.com, undated).
How long can an insurer take to pay or deny a storm claim?
It depends on the state. In Florida, the insurer must pay or deny an initial, reopened, or supplemental property claim, or part of it, within 60 days of receiving notice, unless the delay is caused by factors beyond its control; payment after 60 days bears interest at the rate in section 55.03 (The Florida Senate, 2023). The 2020 version of that statute allowed 90 days (The Florida Senate, 2020).
Can I add damage I discovered after the adjuster left?
Yes. FEMA states that items missed on the Proof of Loss form can be submitted later as a supplemental claim (FEMA, 2025-01-21). In Florida, the 60-day pay-or-deny period applies to reopened and supplemental claims as well as initial ones, counted from notice of that claim (The Florida Senate, 2023). Document the new damage with dated photos and a line-item estimate first.
The payment was less than the insurer's own estimate — what now?
In Florida, if payment is less than the amount in the insurer's detailed estimate of the loss, the insurer must give a reasonable written explanation of the difference (The Florida Senate, 2023). Request it from the claims adjuster in writing, compare it line by line against your contractor or body shop estimate, then consider the appraisal clause in your policy or a complaint to your state insurance department.